Starting an MGA in 2026 means getting four foundational requirements in place before a single policy can bind. Miss any one, and the other three stop mattering.
- A fronting or capacity partner willing to sign a binding authority agreement.
- A license in each target state, issued under that state’s version of the NAIC Managing General Agents Act.
- A rating and risk-selection engine that can demonstrate its logic to the fronting carrier.
- Enough working capital to cover the gap between launch and breakeven.
The market backdrop explains why founders keep attempting it. Aon’s 2025 MGA Market and Outlook put US MGA direct premiums written at $109.2 billion in 2024, roughly 90% growth since 2020, and AM Best counted nearly 800 MGAs meeting the NAIC reporting threshold in 2025. The market is open. Getting through the entry checklist is the hard part.
How each state legally defines an MGA
An MGA is defined state by state, under some version of the NAIC’s Managing General Agents Act (Model #225), which governs licensing, binding authority contracts, fiduciary duties, and audit obligations. There is no single national MGA license.
Each state Department of Insurance runs its own regime:
- California licenses MGAs under Insurance Code sections 769.80 through 769.87.
- Texas licenses them under Insurance Code Chapter 4053.
- Florida governs them under sections 626.7451 through 626.7455 of its statutes.
- Wisconsin regulates them under chapter Ins 42 of its administrative code.
New York adds further financial statement requirements through its Department of Financial Services. Tennessee’s Managing General Agents guidance shows what a single state demands: a licensing packet, specified forms, and a defined set of instructions an MGA must satisfy before it can operate there at all.
A founder building a multi-state book should treat licensing as its own workstream, not an afterthought appended to the business plan. Several states have revised their rules recently: Colorado’s amended surplus lines regulation took effect on January 30, 2026, and Pennsylvania’s current list of eligible surplus lines insurers was published on March 16, 2026. New York adds its own layer through the Department of Financial Services:
- A 3.6% premium tax on surplus lines business, paid by the broker, plus a separate stamping fee charged by the Excess Line Association of New York.
- Documentation that three authorized insurers declined the risk before it can be placed with a non-admitted carrier.
None of this is discretionary. It is the checklist.
Securing capacity is the real gatekeeper
An MGA cannot bind a single policy without a carrier or fronting partner prepared to put its paper behind the program. This step eliminates more startups than any licensing delay does.
The division of labor is simple to state. The MGA designs the product, selects the risks, sets the price, and owns the customer relationship; the licensed insurer provides the regulatory standing and carries the risk with its reinsurance partners. The carrier’s caution follows from that: if the MGA’s book pays out more than it takes in, nothing else about the business matters.
That risk-sharing structure is also where the market has been reorganizing. Gallagher Re’s May 2025 report found that Swiss Re and Munich Re cut back their MGA participation in 2024 while other reinsurers moved up the rankings, even as fronting carriers grew their written premium. Capacity exists, but it sits in different hands than it did a few years ago, and a founder approaching a fronting carrier in 2026 should expect a more selective counterparty.
Building a submission fronting carriers will accept
A fronting carrier grants binding authority only after reviewing the MGA’s underwriting appetite, rating logic, and loss projections in enough detail to trust them with its balance sheet. This is where most weak submissions fail, and where the business plan has to carry more weight than a pitch deck.
The plan must demonstrate four things a fronting partner will require:
- A defined underwriting appetite: which risks the MGA will write and which it will not, with clear reasoning behind those boundaries.
- A rating method supported by actuarial work, not a spreadsheet of estimated loss ratios.
- A claims handling and adjuster routing process that shows the carrier exactly who touches a claim and at what point.
- A compliance and audit trail covering every binding decision, consistent with the fiduciary obligations the NAIC model law imposes.
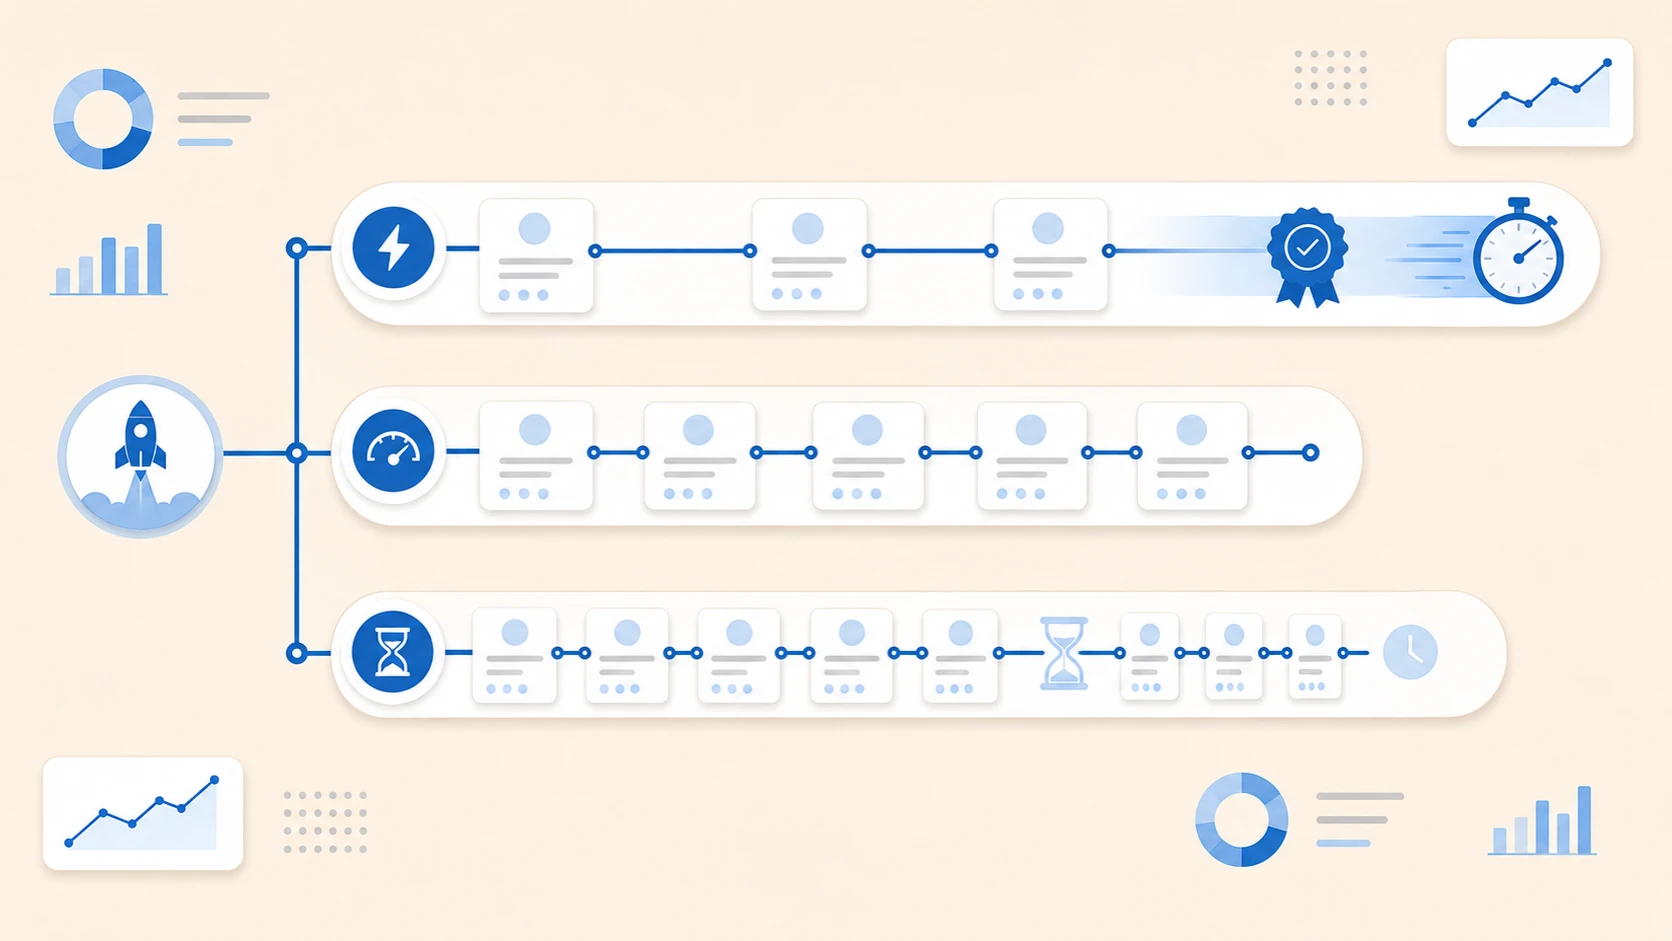
This is where Viola by RegenAI fits the startup MGA problem. Viola’s rating engine can launch a new state in about a week, with every rate versioned and gated for approval; on a manual build, the same work typically takes months. That speed is possible because every rate change carries its own audit trail from the moment it is written. A new MGA has to persuade a skeptical fronting carrier that its underwriting logic is disciplined, and a documented, versioned rating history closes the gap between an interesting pitch and a signed binding agreement.
Talent is also hardest to find exactly when a founder needs it most. At TMPAA’s 2025 conference, executives warned that the MGA boom is outpacing the talent available to run it, with experienced staff retiring even as new MGAs keep forming. When a new MGA competes with established players for the same small pool of experienced underwriters, automated underwriting workflows stop being a convenience and become a necessity.
Sizing the capital requirement and timeline realistically
A new MGA needs enough capital to reach breakeven, not merely enough to open its doors. Founders who underestimate that gap are the ones who run out of runway six months before the fronting relationship starts paying off.
As markets soften, underwriting discipline matters more, not less, and the MGAs best positioned to grow are the ones that pair it with good data and efficient operations. That combination is exactly what a lean founding team struggles to build from scratch while also pursuing licenses and capacity. It is also why Viola runs the full policy lifecycle, from quote through claims settlement, on one platform rather than a stack of point solutions, each with its own implementation budget and vendor contract.
Every month spent on a slow licensing process or a manual rating build is a month a competitor uses to capture share of that growth. The founders who get through this checklist fastest are not the ones with the largest raise. They are the ones who treat licensing, capacity, and underwriting proof as one connected workstream from day one, not three separate problems tackled in sequence.
If you are planning a launch and want to see how the rating and audit side works in practice, talk to us.